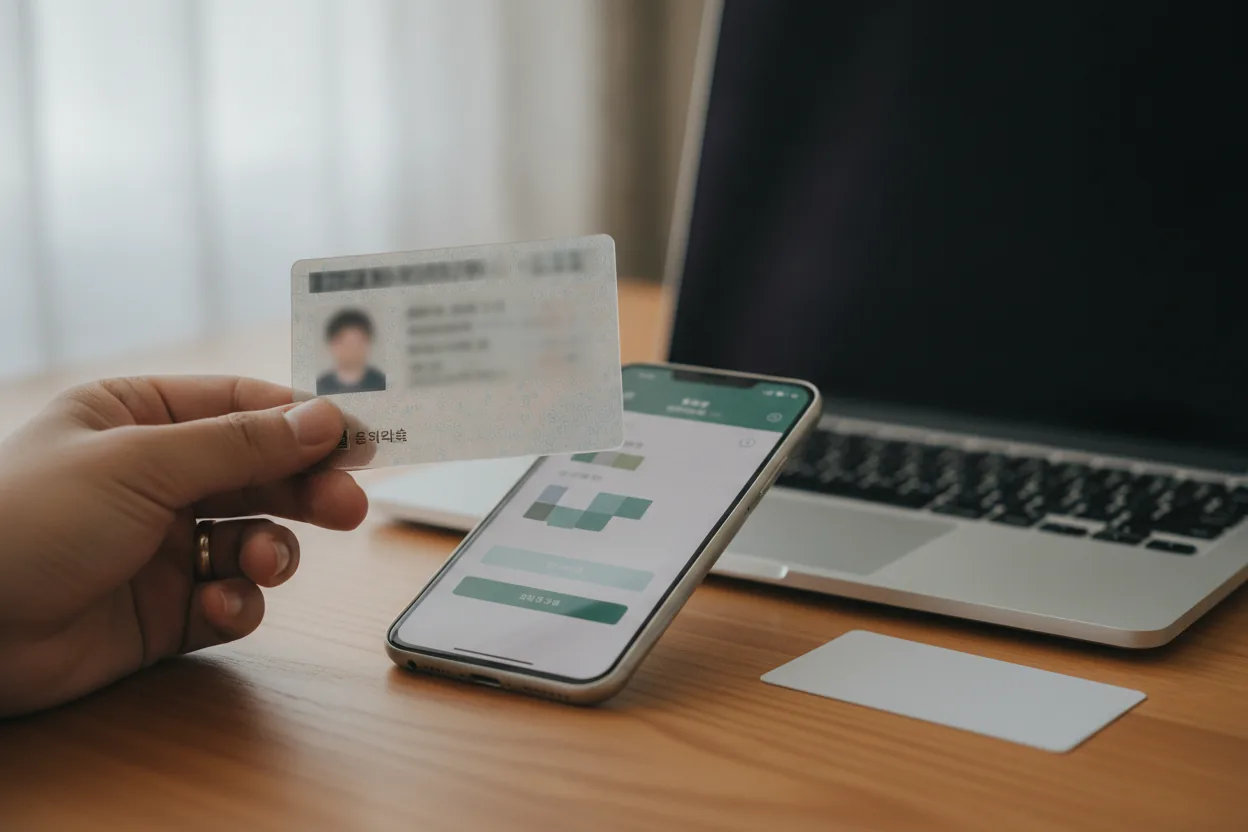
A Canadian teacher's ARC card exposes the resident registration gap in Korean banking
A foreign resident in Korea gets an ARC number instead of a Resident Registration Number. The two formats differ, and plenty of Korean banking systems were built to accept only one of them. KakaoBank, Korea's largest internet-only bank by user base, offers zero deposit products to foreign residents right now. Checking accounts, savings, time deposits, all of it restricted to real-name Korean citizens until a Q4 2026 rollout. Toss Bank solved the same problem years earlier by verifying ARC numbers against Korean mobile numbers. So the real question is whether KakaoBank can close in one quarter a gap that took its competitor years to build.
KakaoBank built its original account infrastructure around RRN verification, full stop. Until its late-2026 product overhaul, most of its core deposit products, including checking accounts, 26-week savings, and time deposits, stayed locked to RRN holders. The bank's own terms classified eligible customers as "real-name Korean citizens," a category that shut out ARC holders structurally, regardless of visa status or how many years someone had lived in the country.
Toss Bank took a different technical path from day one. Its onboarding flow verifies identity using the ARC number paired with a Korean mobile number, which lets the system treat foreign residents as a normal verification case instead of a special exception. The result shows up immediately: Toss can onboard a foreign resident in minutes. KakaoBank can't onboard one at all without building a parallel product from scratch for that exact purpose. One design choice, made years apart between the two banks, now separates how much of Korea's foreign resident market each one can actually reach.
Toss Bank opens an account in minutes while KakaoBank targets a Q4 2026 rollout
That design gap shows up directly in how long it takes a foreign resident to open an account at each bank today. KakaoBank is a publicly listed company in Korea, and for anyone comparing it against Toss Bank's business trajectory, the account-opening gap isn't a minor convenience issue. It's a direct read on each company's addressable customer base. Here's where things stand, step by step.
Toss Bank, fully open to foreign residents today:
- Download the Toss app and begin registration.
- Enter the ARC number in place of an RRN.
- Link a Korean phone number for SMS verification.
- Complete identity verification entirely non-face-to-face.
- The account activates within minutes. No branch visit required.
KakaoBank, currently closed to foreign residents, with change coming in Q4 2026:
- As of August 23, 2026, KakaoBank revised its terms so that checking accounts, savings accounts, time deposits, flexible savings, 26-week savings, record accounts, and personal business accounts are explicitly limited to real-name Korean citizens.
- According to Chosun Biz reporting from October 3, 2026, KakaoBank plans to launch dedicated checking and savings accounts, debit cards, and overseas remittance and foreign exchange services for foreign residents in the fourth quarter of 2026.
- The bank intends to run the entire sign-up and usage process non-face-to-face, mirroring the Toss model rather than requiring branch visits.
- A KakaoBank official said the terms revision was preparatory work, not a tightening of existing conditions, ahead of the foreigner-specific launch.
The sequencing here matters a lot for anyone newly arrived in Korea. Relocation guides lay out a practical order: ARC appointment within the first one to three days of arrival, ARC card issued within seven to fourteen days, bank account opened around day fourteen to sixteen, Korean phone plan secured in that same window, then mobile banking and Kakao Pay setup, followed by 전입신고 (address registration) at the local 주민센터. Toss Bank slots cleanly into day fourteen to sixteen for foreign residents today. KakaoBank doesn't fit into that sequence at all under current rules, not until the Q4 2026 products actually launch.
One workaround already exists, and it's worth separating from the account issue entirely: Kakao Pay, the payment service, works with any other Korean bank account, including Toss Bank, Shinhan, Woori, or KEB Hana. A foreign resident doesn't need a KakaoBank account to use Kakao Pay for daily transfers or QR payments. The restriction sits specifically at the deposit-account level, not the payment-app level.
KakaoBank's Q4 2026 launch date is the number investors should track
The same timeline that decides whether a new arrival can bank with KakaoBank in time also decides what the company is actually worth to investors watching this segment. The bank has run with zero dedicated foreign-resident products up to this point, which means its entire addressable market among Korea's foreign resident population, a group that's grown steadily alongside work-visa and E-7 inflows, has effectively been served by competitors instead. Toss Bank's head start here, dating back to its original ARC-based verification design, represents years of accumulated foreign-customer relationships that KakaoBank is now trying to challenge from a standing start, in a single quarter. Whether that's enough time will show up first in KakaoBank's own Q4 2026 product launch, not in some later announcement. If the checking accounts, debit cards, and remittance services ship on schedule and the non-face-to-face process works as described, KakaoBank closes a gap that took its competitor years to build. If the date slips, the gap holds, and Toss Bank's head start compounds for another quarter.